Most people don’t fail at saving because they lack discipline. They fail because saving depends on a decision they have to make again and again, usually at the worst possible moment. Money arrives, bills compete for it, and whatever is left at the end of the month rarely looks like enough to bother setting aside. Good intentions fade under that kind of pressure.
Automation removes the repeated decision. You choose once, set the rules, and let your accounts do the work on schedule. The setup takes less time than a lunch break, and once it’s running, your savings grow whether you’re paying attention or not. The rest of this article walks through how to build that system, step by step.
Why Willpower Is the Wrong Tool
Saving by hand asks you to act against your own habits every payday. That is a tough fight to win twelve times a year, let alone twenty-six.
Research backs this up. The Federal Reserve’s annual Survey of Household Economics and Decisionmaking regularly finds that a large share of adults would struggle to cover a modest surprise expense with cash. Many of those people earn enough to save. What they lack is a system that moves the money before daily spending gets to it.
That’s the core idea behind “paying yourself first.” Savings stop being leftovers. They become the first bill you pay.
Step One: Pick Where the Money Will Live
Before you move a single dollar, you need a destination. The account you choose shapes how well the whole setup works, so spend two of your ten minutes here.
Choose a Separate Account
Keep savings apart from checking. When both sit in the same place, the balance looks like spending money, and it tends to get spent. A separate account, ideally at a different bank, adds just enough friction to stop impulse withdrawals.
Look for Interest and Insurance
A high-yield savings account pays far more than a standard one, and the gap adds up over years. Confirm the bank is covered by federal deposit insurance. The FDIC explains how deposit insurance works and what limits apply, which is worth a quick read if you plan to hold a large balance.
Skip the Fees
Monthly maintenance charges quietly eat into small balances. Pick an account with no minimum balance and no monthly fee, especially while you’re building from zero.
Step Two: Decide How Much to Move
With the account ready, the next question is the amount. Here, starting small beats starting perfectly.
Start With a Number You Won’t Miss
Pick an amount low enough that you won’t cancel the transfer the first tight month. Even twenty-five dollars per paycheck builds a habit. You can raise it later, and you will.
Use a Percentage If Your Income Varies
Freelancers and hourly workers often do better saving a fixed share, such as 5 or 10 percent, rather than a flat amount. The transfer shrinks in lean months and grows in strong ones. Nothing breaks.
Plan for Raises in Advance
Here is a trick few people use. Decide now that half of every future raise goes straight to savings. When the raise lands, you bump the transfer before your spending has a chance to expand.
Step Three: Set the Transfer to Match Payday
Timing matters more than most people think. A transfer that runs on the wrong day can overdraw your checking account and sour you on the whole plan.
Schedule It the Day After Payday
Set the recurring transfer for one day after your paycheck clears. The money arrives, then leaves for savings before you can touch it. That one-day buffer protects you if a deposit posts late.
Split Your Direct Deposit Instead
Many employers let you divide your paycheck across accounts. Ask payroll to send a set amount straight to savings. This version is even cleaner, since the money never passes through checking at all.
Automate Retirement Too
If your employer offers a retirement plan, enroll and set your contribution. Grab any match first; it’s the closest thing to free money most workers will see. To see how steady contributions compound over decades, try the SEC’s compound interest calculator. The long-term numbers are often the push people need.
Step Four: Let AI Guidance Sharpen the Plan
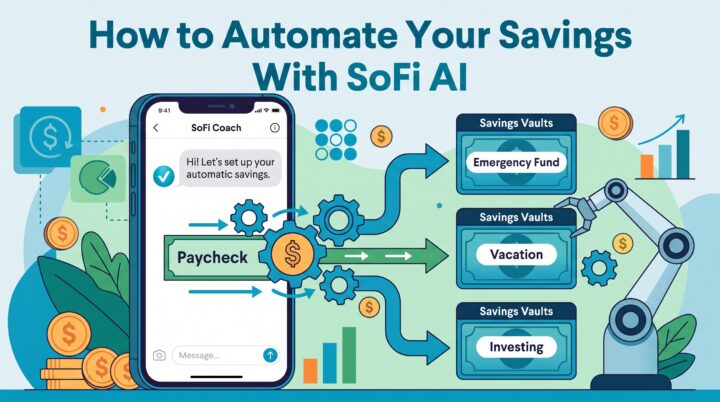
A basic automated transfer works on its own. Still, knowing how much to save and where to save it gets easier with a second opinion, and AI advisory tools now offer that for little or no cost.
Traditional financial advice used to require a paid appointment and a certain account size. That shut out many people who needed guidance the most. Tools like an AI financial planner can look at your income, expenses, and goals, then suggest a transfer amount that fits your real cash flow instead of a rule of thumb. They can also flag when your emergency fund is large enough, and extra money might work harder in a retirement account or toward high-interest debt.
The real value is speed and access. You can ask a follow-up question at midnight, test a few scenarios, and adjust your transfer before your next paycheck arrives. Treat the output as a starting point, though. Check big decisions against your own judgment, and bring in a licensed professional for complex matters like taxes or estate planning.
Step Five: Build in Checkpoints
Automation handles the routine. Short, scheduled reviews keep the system honest and aligned with your life as it changes.
Set a Quarterly Reminder
Put a fifteen-minute review on your calendar every three months. Look at your balance, confirm the transfers ran, and ask whether the amount still fits. Life shifts. Your plan should shift with it.
Name Your Goals
Many banks let you split savings into labeled buckets, like “car repair” or “summer trip.” Named goals are harder to raid. Pulling from “emergency fund” to buy concert tickets feels different than pulling from a generic balance.
Watch for Overdrafts
If a transfer ever triggers an overdraft, don’t cancel it. Lower it, or move the date. The goal is a plan you can keep running, not one that looks impressive for a month.
Common Mistakes to Avoid
Even a simple system can stall. Most problems trace back to a few predictable errors.
Setting the amount too high is the most common. People get motivated, pick an aggressive number, and then pause the transfer after one rough month. Pausing turns into stopping.
Another mistake is treating savings as a checking backup. If you dip in every time your balance runs low, the account never grows. Keep a small cushion in checking so savings can stay untouched.
The last one is forgetting the plan exists. Automation is meant to run quietly, but “quiet” shouldn’t mean “ignored.” Your quarterly check-in prevents that drift.
Conclusion
Automating your savings turns a monthly struggle into a background process. Once the account is chosen, the amount is set, and the transfer is timed to payday, saving no longer depends on willpower or memory. Guidance tools can help fine-tune the numbers, and brief, regular reviews keep everything on track. The setup takes only a few minutes, but the habit it creates can shape your finances for years.